PRIVATE ESTATE BANKING
The capital warehouse.
Cash value whole life, coordinated with estate ownership, funding, access, and the next generation. A strategy you learn to operate.
EXPLORE THIS STRATEGY WEALTH STRATEGIST GROUP
THE ESTATE CAPITAL ENGINE
Built Around Your Life. Powered by Cash Value Whole Life.
You traded time for the capital you have. Give that sacrifice a lifetime purpose. Your estate, your accounting, and your strategist work from the same map.
BOOK YOUR PRIVATE WORKSHOPGive your capital a home and a long-term purpose.
Bring existing retirement capital into the plan.
Get expensive creditors out of your back pocket.
Learn the next move after the estate has its footing.
THREE TOOLS / ONE CAPITAL STRATEGY
Whole life creates the warehouse. Fixed indexed annuities give eligible capital a staging role. ROBS can connect eligible retirement capital to a real business. The protocol brings the tools together, then teaches you how to use them.
PRIVATE ESTATE BANKING
Cash value whole life, coordinated with estate ownership, funding, access, and the next generation. A strategy you learn to operate.
EXPLORE THIS STRATEGYFIA / CAPITAL STAGING
A disciplined contract-selection process: the S&P 500 index strategy, participation, cap, floor, and access terms. Capital staging has a purpose inside your full estate plan.
EXPLORE THIS STRATEGYROBS / BUSINESS FUNDING
Examine whether eligible retirement funds can support a real operating business through a properly administered retirement-plan structure.
EXPLORE THIS STRATEGY01 / PRIVATE ESTATE BANKING
You already know how to earn. The question is whether the banking function around your capital serves the life you are building. We sit down with your numbers and examine that function together.
THE FOUNDATION / AUSTRIAN ECONOMICS
The dollar is the receipt.
The sacrifice was your time.
Austrian economics informs how we think about capital: private property, voluntary exchange, and the judgment of the individual. Chapter Seven of The Art of Passing the Torch follows that intellectual lineage through Menger, Mises, Hayek, and Leonard Read to R. Nelson Nash and the banking function.
For us, that philosophy starts at your kitchen table. You traded hours you cannot recover for the capital you have. The question is what that capital will do for your family from here.
Give saving a purpose before the next expense claims the dollar.
Know the cost of capital, the access terms, and the job each deployment must do.
Teach the next generation the discipline alongside the architecture.
Our faith gives that work its purpose: free will, responsibility, and stewardship. The economics informs how we think about capital. The family gives us the reason to build.
THE ART OF PASSING THE TORCHA participating cash value whole life policy can serve as a capital warehouse coordinated with your estate. We examine ownership, premium funding, available cash value, and the purpose of future access as one strategy.
Available value may secure policy loans while the policy remains in force. Loan interest, dividends, repayment, and the effect on the death benefit are part of the same conversation. You see the mechanics before you decide how the contract fits.
Your strategist brings your situation into the custom workshop app. We work through funding assumptions, coverage, paid-up additions, guaranteed values, non-guaranteed dividends, and the cost of accessing capital.
Then we map the deployment. Which creditor is taking the most from your cash flow? What does a policy loan actually cost? Which business, property, or lending opportunity deserves capital? You leave with a map and coaching to understand the next move.
INSIDE THE LIVE WORKSHOP
Explore the sample screens below. In your workshop, we work through your circumstances and the supporting carrier information.
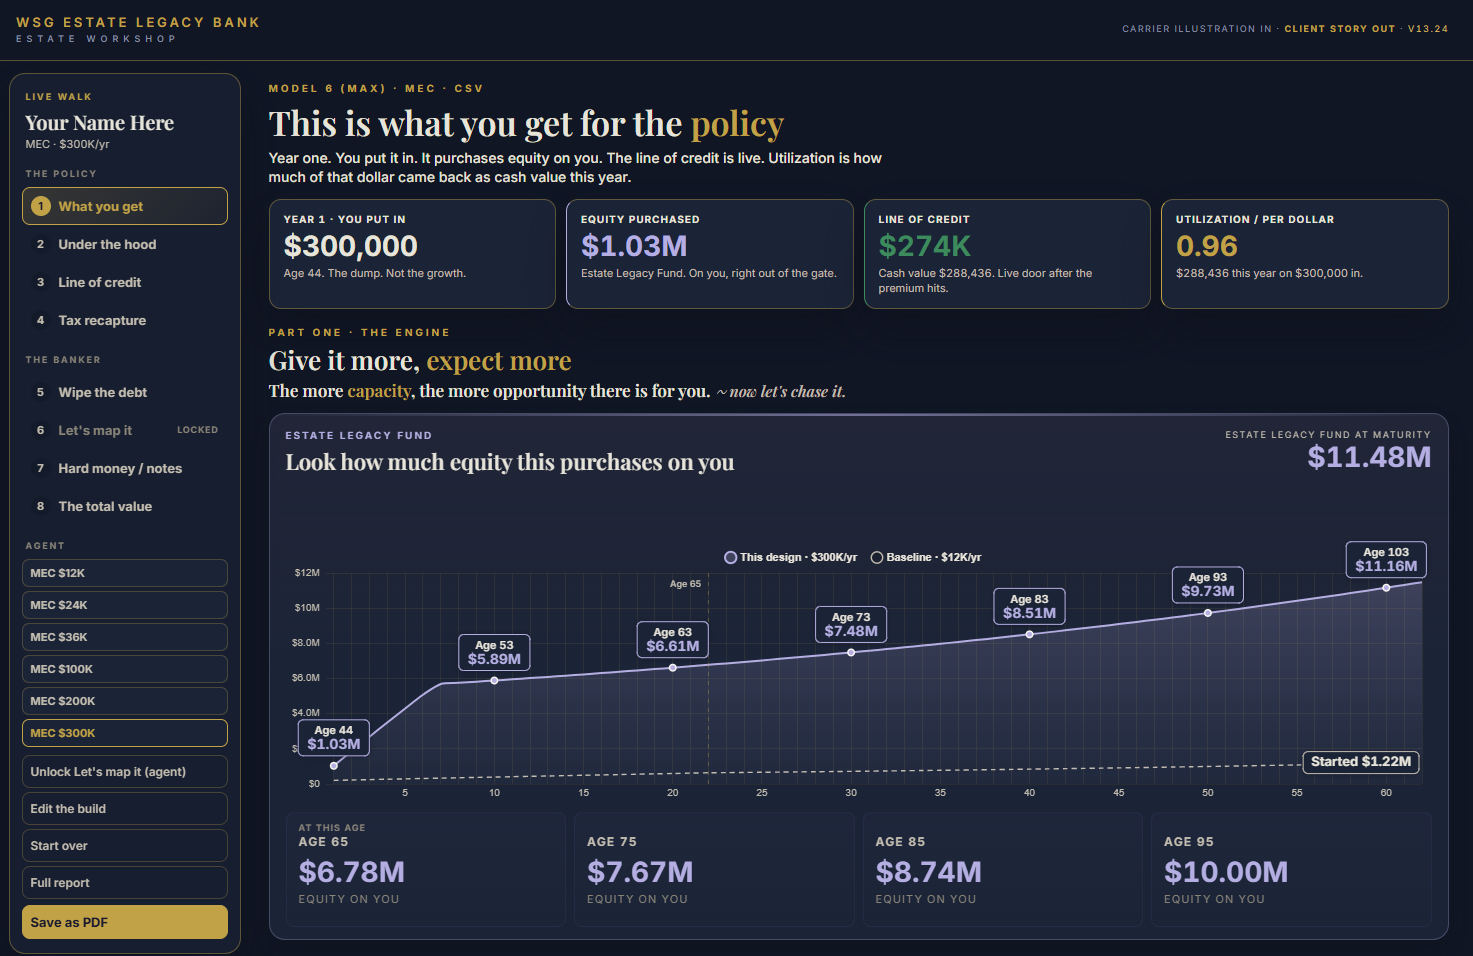
Sample app scenario, not a personal or carrier illustration. Assumptions and values are reviewed in your workshop. Select the image to view it at full size.
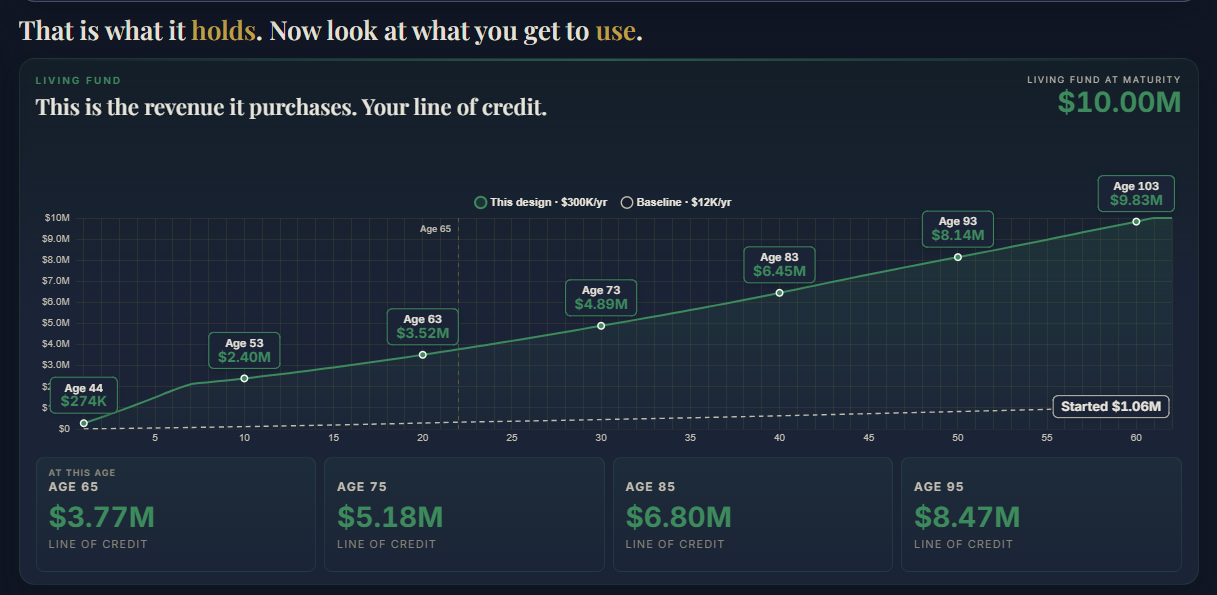
Illustrative capital-access model. Actual borrowing depends on available policy value and contract terms; loans accrue interest. Select the image to view it at full size.
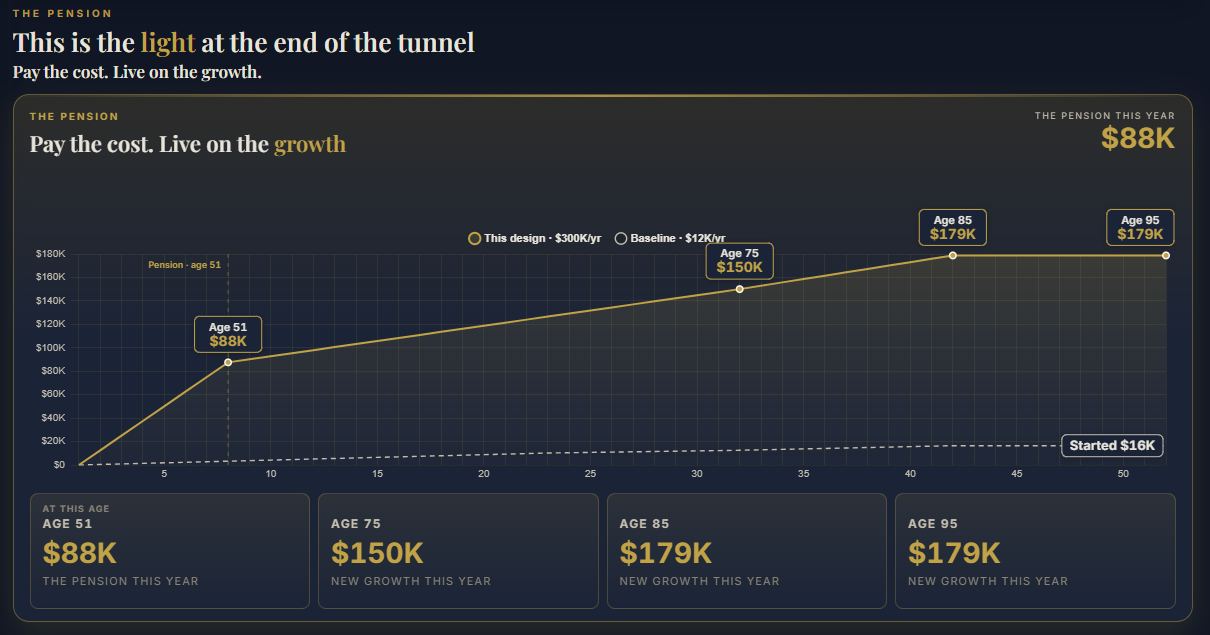
Modeled annual growth, not a guaranteed pension payment. Funding, access costs, and tax treatment are reviewed separately. Select the image to view it at full size.
DRAFT MODEL · ACCOUNTING REVIEW REQUIRED
This draft screen assumes a 100% reduction of prior business tax. That result is not established. Allocating income to trust corpus under §643 does not itself eliminate federal income tax. Contribution eligibility, deduction limits and each household’s tax treatment must be reviewed by qualified tax professionals before any savings enter the funding plan.
Read the IRS explanation of §643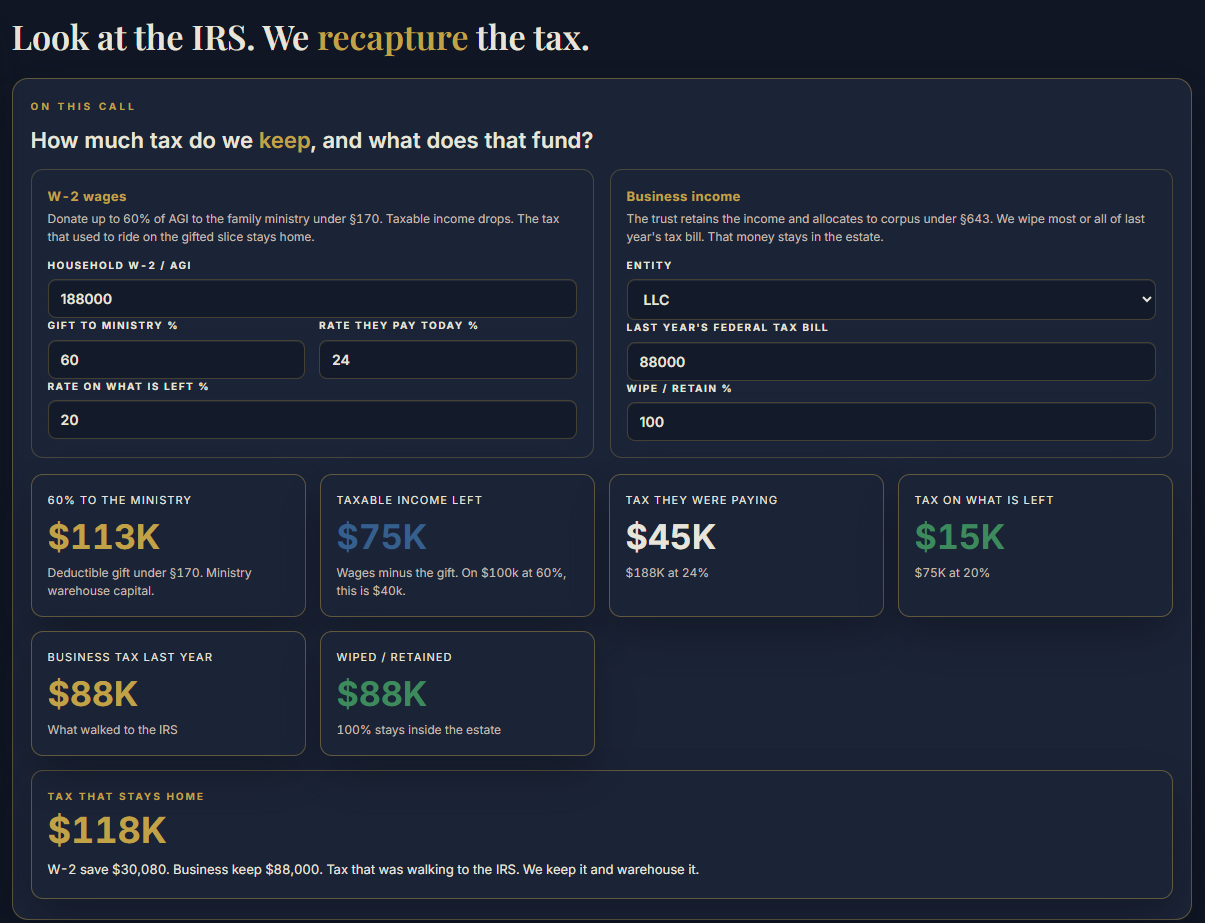
Draft interface preview. The tax reductions shown are unverified assumptions and must not be relied on as expected results.
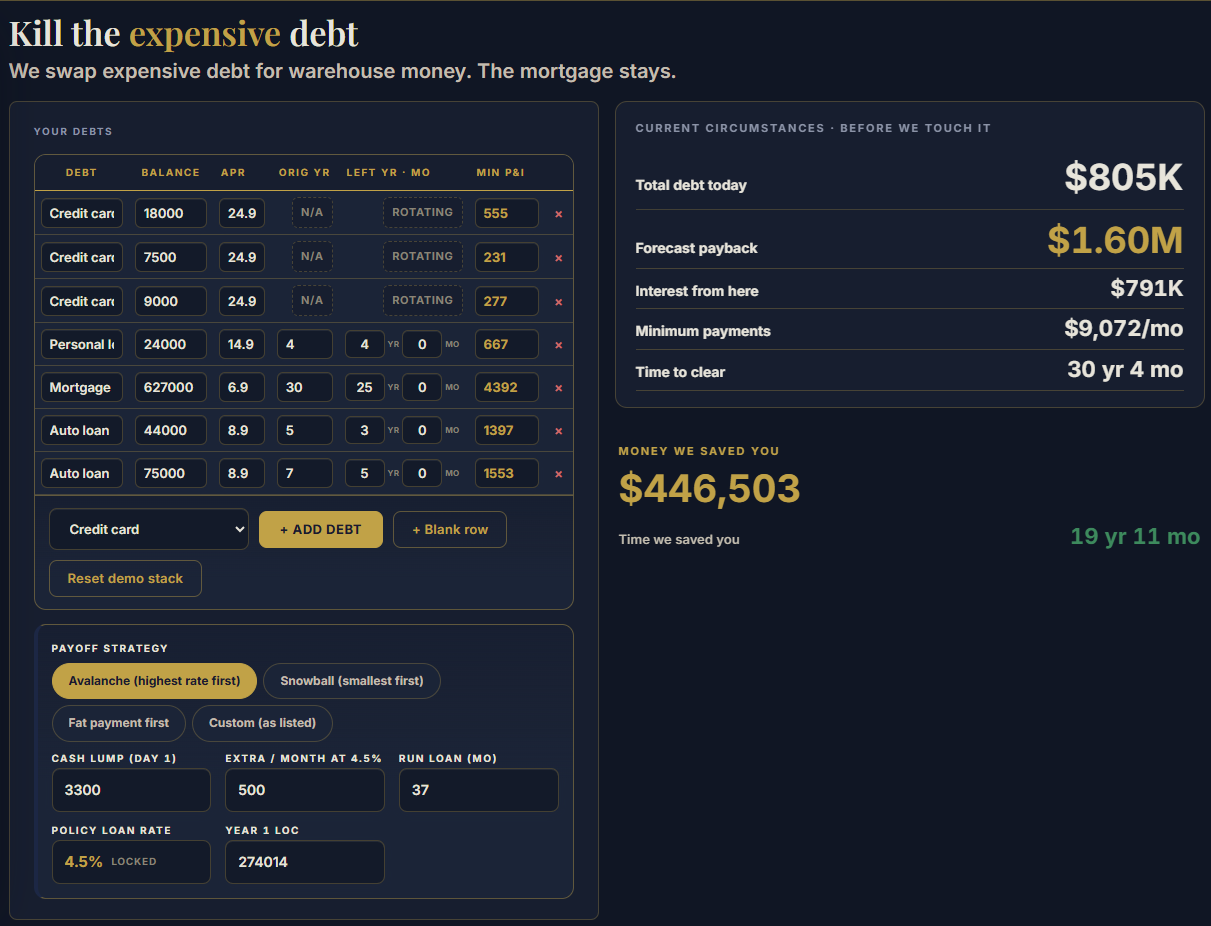
Hypothetical debt-payoff comparison. Savings, timing, and the 4.5% loan rate shown are model assumptions, not quoted terms or promised results. Select the image to view it at full size.
THE TAX AND FUNDING REVIEW
We review the existing accounts, income, liquidity, and funding capacity with you. The accounting team evaluates tax treatment against your actual records. A workshop assumption becomes a decision only after the underlying facts, contracts, and professional review support it.
02 / RESCUE THE RETIREMENT
The dollar is not just an account balance. It is the hours you already spent. Our FIA work gives eligible capital a defined role: stage it deliberately, understand its access schedule, and coordinate the next move with the warehouse beside it. Catching the recovery means planning the buyback: having accessible capital ready to consider assets when prices become attractive, with the timing and risk reviewed together.
A HIGH STANDARD FOR THE CONTRACT
We focus on fixed indexed annuity strategies offering 100% participation in the S&P 500 price index, subject to the contract’s cap and crediting method. You should understand exactly which index is being measured and how a credit reaches your account.
A large participation headline on a different index is a different calculation. We compare the actual index, cap, spreads, fees, renewal terms, and access provisions together. We start with your situation and compare the vehicles on your dollars. The right contract earns its place by the value it brings to your plan.
THE FLOOR
A 0% index-crediting floor means negative index performance produces no negative index interest credit. Fees, withdrawals, surrender charges, and applicable adjustments can still reduce contract value. Guarantees depend on the insurer’s claims-paying ability.
THE ACCUMULATION JOB
A large bonus or participation percentage is the beginning of the review. Read the index name first. Participation on a volatility-controlled index is a different calculation from participation in the S&P 500 price index. Then compare caps, spreads, fees, renewal terms, and access. We show you the trade-offs before you sign.
THE ACCESS PLAN
The whole life warehouse and FIA have distinct access terms. We coordinate liquidity, withdrawal allowances, surrender periods, and tax considerations before capital is staged.
THE RETIREMENT REVIEW
We bring existing retirement accounts, income needs, and future capital uses into one conversation. Qualified and non-qualified money are handled separately. Eligible transfers and rollovers are coordinated with the appropriate professionals.
03 / ROBS BUSINESS FUNDING
Rescuing retirement can mean giving eligible funds an operating purpose. If you are building or acquiring a business, we examine whether Rollover as Business Startups can support it through a properly structured C corporation and qualified plan. The business case, retirement exposure, and continuing administration all belong in the decision.
What is being built or acquired? What capital does it require? How will it operate? We work through the intended use of funds and the people who will be responsible for execution.
ROBS is not a passive escape from a retirement account. The business has to justify putting retirement capital at risk.
In a properly structured ROBS arrangement, eligible retirement funds roll into a qualified plan sponsored by a C corporation. The plan purchases corporate stock, and the corporation receives operating capital.
The retirement plan owns those shares. Business losses can reduce the value of the retirement investment.
The retirement plan needs continuing administration, valuation, employee-eligibility review, and filing discipline. We coordinate the appropriate specialists and accounting work.
The funding event is the beginning of those responsibilities. Your team helps you understand the operating calendar before you commit.
04 / THE DEPLOYMENT DISCIPLINE
Before we talk about leveraging for wealth, we look at what is compounding against you. The first deployment job is to examine expensive third-party debt, recapture interest where the numbers support it, and put that cash flow back to work inside your own strategy.
01 / RECLAIM CASH FLOW
Bring the balances, rates, payments, and payoff terms. We compare existing debt with the full cost of policy borrowing. When the numbers support it, a planned payoff can reduce interest paid to third-party lenders and bring freed cash flow back into your estate capital strategy.
We model policy borrowing instead of withdrawing policy value, including how the selected contract treats growth while a loan is outstanding. Loan costs and repayment still matter. The objective is fewer expensive obligations, more room in the monthly cash flow, and a stronger estate before the next investment.
02 / LEARN THE SPREAD
We teach the relationship between borrowing costs, cash flow, and the expected economics of a deployment. A projected return above the loan rate needs closer examination. It does not establish that an investment will be profitable.
Interest, fees, taxes, timing, liquidity, and losses all enter the calculation. Your capital map shows the tradeoffs before you commit.
03 / GIVE CAPITAL A JOB
Business funding. A property acquisition. A carefully evaluated lending opportunity. Each deployment needs a use of funds, repayment source, reserve plan, and exit.
Borrowing against policy value does not make deployed capital risk-free. Loans accrue interest and can reduce available value and death benefits. The strategy requires active stewardship.
THE NEXT LESSON / THE NEXT OPPORTUNITY
You do not need to arrive as an expert. You do need to be willing to understand what your dollars are being asked to do.
Learn to examine the borrower, collateral, loan-to-value, lien position, documents, and repayment source. Interest income has to be evaluated alongside default risk, expenses, and the time capital may be tied up.
Different operators serve different markets. We help you examine the demographic, acquisition basis, operating cash flow, leverage, reserves, and exit alongside the projected upside.
Evaluate the use of funds, operating plan, and return of capital. Your strategist, accounting team, and appropriate professionals connect the deployment back to the estate’s records and responsibilities.
THE PRIVATE COMMUNITY / CORNERSTONE CAPITAL
Our relationship with Cornerstone Capital connects the WSG community with education and conversations around real estate operators, private lending, and syndications. It is another part of the ecosystem built around families who want to understand how capital can work.
Cornerstone Capital participation starts with the trust. An established trust is a prerequisite to consideration; it is not automatic admission or investment eligibility. Each opportunity has its own review, documents, suitability requirements, and risks.
01Establish the estate architecture.
02Learn the deployment discipline.
03Explore the community with the team.
This page invites educational interest. No specific investment is offered here. Private investments can be illiquid and can lose capital. Joining the list does not reserve an allocation or obligate you to invest.
STAY IN THE CONVERSATION
Hear about education, community conversations, and opportunities to learn more about Cornerstone Capital.
THE ENGAGEMENT
Structure the estate. Stage the capital. Learn the deployment. Keep the records. Your strategist, accounting support, education, and community work together around the life you are building.
Existing policies. Retirement accounts. Business capital needs. Debt obligations. Family priorities. We start with what you have and what you need it to do.
Personalized illustrations where appropriate, ownership and funding coordination, and a clear calendar of access, tax-review, and operating responsibilities.
You bring the records and the willingness to learn. We bring the strategist, accounting coordination, and coaching. The work continues as your circumstances evolve.
YOUR PRIVATE WORKSHOP
Walk us through your situation. Let us show you how the capital strategy could fit your estate, your retirement, and the next chapter you are building. No obligation. No pressure. Just clarity.
BOOK YOUR PRIVATE WORKSHOPYOUR FIRST STEP
Get the free guide to the architecture and the team behind it. Read it at your pace, then request a consultation when you are ready.